What is the market overview and industry significance of the Solar Control Glass Market?
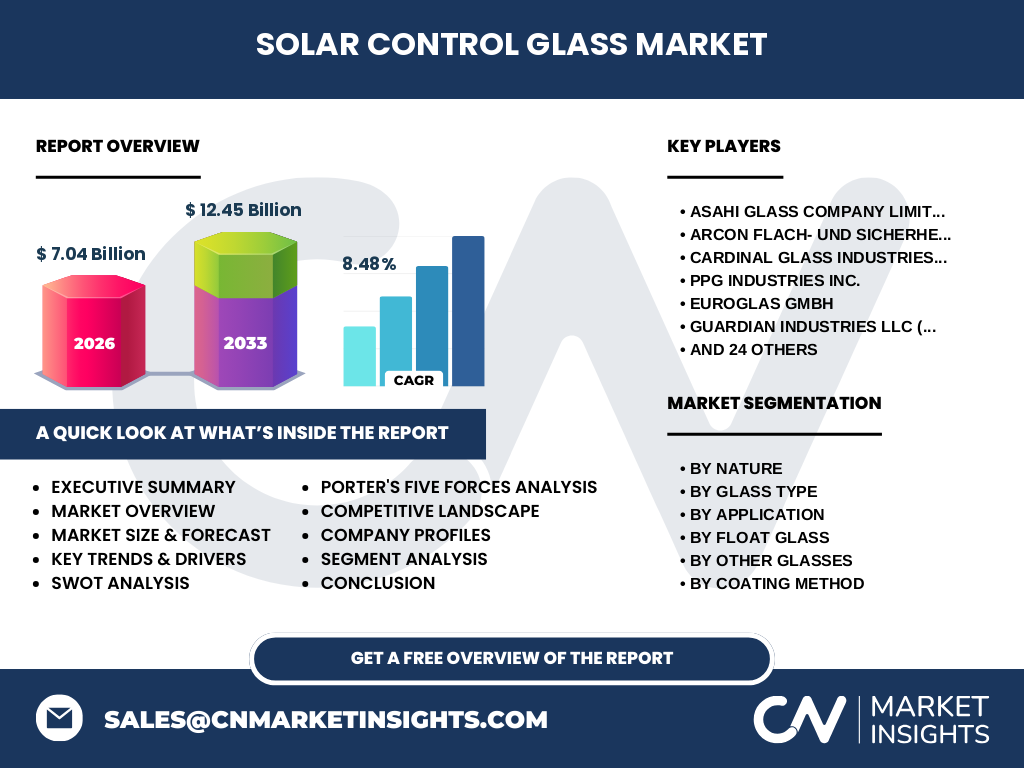
Our analysis indicates that the Solar Control Glass Market size is valued at $7.04 Billion in 2026. This specialized sector focuses on advanced architectural and automotive glazing that minimizes solar heat gain while maximizing visible light transmission, directly addressing stringent building energy codes governed by bodies like the U.S. Department of Energy.
Key market drivers, restraints, challenges, and opportunities shaping Solar Control Glass Market
The market is propelled by strict net-zero carbon building mandates and soaring demand for low-emissivity coatings. However, high capital expenditure for vacuum-coating lines and raw material volatility for compounds like silver and tin oxide act as primary restraints. Significant opportunities lie in retrofitting aging commercial skylights with high-performance insulated glass units.
The Shift Toward Smart Glazing Technologies
Industry trends reveal an aggressive pivot toward dynamic, responsive facades. Electrochromic and photochromic configurations are gaining traction over static panes, allowing commercial real estate developers to dynamically control solar heat gain coefficients and reduce HVAC loads in response to shifting solar irradiance.
How did the COVID-19 pandemic impact the Solar Control Glass Market and its recovery trajectory?
Supply chain bottlenecks for float glass and disrupted architectural project timelines caused temporary contraction during the pandemic. Recovery has been robustly steered by post-pandemic stimulus packages favoring green building upgrades, driving a sharp rebound for major suppliers like Saint-Gobain S.A. and Guardian Industries LLC.
Competitive Benchmarking and Market Concentration
The competitive landscape is moderately consolidated, dominated by Tier-1 innovators such as Asahi Glass Company Limited, Nippon Sheet Glass Company Limited, and Vitro Architectural Glass. These industry leaders leverage proprietary magnetron sputter vacuum deposition (MSVD) coating technologies to maintain pricing power and defend their market share against aggressive regional challengers.
Executive Summary of the Solar Control Glass Market
This comprehensive report projects the Solar Control Glass Market to expand to $12.45 Billion by 2033, registering a robust CAGR of 8.48% from 2027 to 2033. Accelerated urbanization, stricter thermal insulation norms, and a growing automotive preference for panoramic sunroofs are the core pillars anchoring this growth.
Market Forecast and Long-Term Growth Trajectory
Driven by the commercial sector's commitment to LEED and BREEAM certifications, the market is poised for accelerated adoption. Our forecasting models show that expanding deployment across emerging Asian economies will consistently outpace traditional European replacement cycles throughout the 2027 to 2033 forecast window.
Segmentation Analysis of Solar Control Glass Market
Market segmentation spans nature (electrochromic, photochromic, gasochromic), glass type (float, heat-strengthened, laminated, tempered), and application (residential, commercial, automotive). Commercial applications dominate revenue generation, driven by skyscraper curtain walls requiring complex insulated glass units with soft-coated low-E configurations.
Geographic Distribution and Regional Performance
Regional performance varies significantly due to local climatic conditions and energy regulations. North America and Europe lead in advanced tech adoption like electrochromic smart glass, whereas Asia-Pacific commands volume consumption, fueled by mass residential and commercial construction booms in urban centers.
In-Depth Regional Review of High-Growth Hubs
Asia-Pacific represents the epicenter of volume demand, bolstered by manufacturing hubs in China and regional innovators like Taiwan Glass Group and Xinyi Glass Holdings Limited. Meanwhile, North American demand centers heavily on commercial retrofitting, complying with ASHRAE 90.1 energy efficiency standards.
Strategic Positioning of Leading Companies
Industry stalwarts like Cardinal Glass Industries Inc. and Schott AG focus on high-purity pyrolytic and vacuum-deposited coatings. Firms such as Sisecam and Fuyao Glass Industry Group Company Limited strategically integrate upstream float glass production with downstream automotive and architectural fabrication to optimize operational margins.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of suppliers is moderate due to specialized raw material requirements for solar control metallic interlayers. Competitive rivalry remains high, forcing manufacturers to continuously innovate coating durability, while the threat of substitutes is mitigated by building codes mandating specific solar heat gain performance.
SWOT Analysis of the Solar Control Glass Industry
Strengths include superior thermal insulation and energy-saving capabilities. Weaknesses stem from high initial manufacturing costs. Opportunities lie in zero-energy building mandates, while threats involve macroeconomic construction slowdowns and trade tariffs on imported raw float glass.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw silica sand, soda ash, and limestone processing into float glass. This substrate moves through advanced chemical vapor deposition or sputtering coating lines managed by firms like PPG Industries Inc. and Viracon Inc., culminating in distribution to commercial curtain wall installers and automotive assembly lines.
Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in soft-coated low-E insulated glass units and integrated smart glass systems. High-growth potential resides in companies successfully scaling durable electrochromic solutions for zero-energy commercial retrofits in urban metropolitan regions.
Conclusion and Strategic Key Takeaways
The Solar Control Glass Market presents compelling investment fundamentals, underpinned by an 8.48% CAGR pushing the market to $12.45 Billion by 2033. Stakeholders must prioritize R&D in energy-efficient coatings and expand manufacturing footprints in developing Asian economies to capture surging demand.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with C-level executives at firms like Euroglas GmbH and Central Glass Company Limited, and secondary macroeconomic indicators from construction output indices and international energy agencies.
Scope of the Report and Coverage Parameters
This report evaluates the global Solar Control Glass Market across historical data points, the 2026 baseline of $7.04 Billion, and a forecast horizon extending to 2033. Limitations include localized building code revisions and unpredicted macroeconomic supply shocks affecting primary raw material logistics.
Recent Industry Developments and Strategic Moves
Recent market activity highlights heavy investments in sustainable manufacturing. Key players have announced multi-million-dollar plant expansions focused on low-carbon float glass production, alongside strategic joint ventures aimed at scaling dynamic electrochromic and coated glass portfolios for next-generation net-zero commercial architecture.